
Your VAT returns
stress-free
Your Swiss VAT returns, stress-free and error-free with
- Liability from CHF 100,000 annual turnover
- Three current rates: 8.1%, 3.8% and 2.6%
- Effective method or NFTR depending on your profile
What is VAT and how does the VAT return work?
VAT (Value Added Tax) is an indirect tax applied to the majority of goods and services supplied by Swiss companies. In practice, companies charge VAT on their sales and may deduct VAT paid on their business purchases. The difference between VAT charged and deductible input VAT is then declared and paid to the Federal Tax Administration by means of a VAT return. A clear understanding of this mechanism is essential, as any calculation error or VAT declaration error may result in adjustments, interest or tax penalties. This is why the VAT return must be prepared with rigour and on the basis of up-to-date accounting records.
Who is subject to VAT in Switzerland?
| Determining whether your activity is subject to VAT | Understanding VAT to better comply with your obligations |
|---|---|
| Companies whose annual turnover exceeds CHF 100,000. They must register with the Swiss tax authorities and charge VAT on their sales. | Foreign companies supplying goods or services in Switzerland. Even without an establishment in Switzerland, they are subject to VAT if their turnover exceeds the legal threshold. |
| Certain VAT-exempt activities, in particular medical, social, financial, cultural or educational activities. | Companies carrying out an exempt activity may opt for voluntary registration. This allows them to recover VAT paid on business purchases, subject to certain conditions. |
When setting up your company, do you need to register for VAT?
- Exceeding a turnover of CHF 100,000. VAT registration then becomes mandatory.
- Making a realistic projection for the first months of activity. If the projection for the next 12 months exceeds the threshold, the company must register with the FTA.
- Choosing voluntary VAT registration. This option may be relevant to recover VAT on investments and expenses, provided it is properly analysed.
What are the Swiss VAT rates in force (from) 2024?
| Taux | % | S'applique à |
|---|---|---|
| Standard rate | 8,1 % | This rate applies to most goods and services, including everyday consumer products such as clothing, electronic devices, catering services, IT services, etc. |
| Special rate | 3,8 % | The special rate for accommodation services applies to overnight stays with breakfast, even if breakfast is invoiced separately. |
| Reduced rate | 2,6 % | This rate applies to certain goods and services considered essential, such as basic food products, prescription medicines, newspapers and magazines, as well as public transport. |
| VAT exemption | 0,0 % | In Switzerland, certain goods and services benefit from an exemption from Value Added Tax (VAT). This exemption applies in particular to insurance and reinsurance transactions, financial transactions, medical services, educational services, the sale and leasing of building land, real estate transactions, as well as postal and telecommunication services of Swiss Post. Social and cultural services provided by non-profit organisations are also exempt. Swiss companies that export goods may also benefit from this VAT exemption, allowing them to remain competitive on international markets. |
Within 48 hours, an expert shows you how to secure your VAT returns, avoid errors and comply with your tax obligations.
Free VAT assessment for Swiss entrepreneurs
Free 30-min diagnosisFree • No commitment • Response within 24h • 100% confidential data
Methods and modes of the Swiss VAT return
1. The two calculation methods (the “How much”)
The method determines how the net amount payable to the Federal Tax Administration (FTA) is calculated:
| Principle | Who can use it | Advantage | |
|---|---|---|---|
| Effective method | This is the standard method. You charge effective VAT to your customers and deduct the VAT paid on your own business purchases (input tax). You pay only the difference to the FTA. | Any taxable person. This is the method applied by default. | Ideal if you have significant investments or expenses (purchase of goods, rent, IT costs). |
| Net Tax Rate (TDFN) | This simplified method is reserved for SMEs. You do not deduct input tax. The tax due is determined by multiplying the total taxable turnover by the TDFN applicable to the sector or activity concerned. | the annual turnover from taxable supplies (VAT included) does not exceed CHF 5.024 million ; the tax due does not exceed CHF 108,000 per year. | Ultra-simple administrative management and VAT returns only twice a year (semi-annually). |
| Flat rates (TaF) | As with the TDFN, input tax is not deducted: the tax due is calculated by applying the flat rate for the activity to the turnover. | Public bodies and related sectors (private schools and hospitals, public transport companies, etc.), as well as associations and foundations, may apply the flat-rate method, regardless of the amount of their turnover. However, the use of the TDFN method is not permitted. | A simplified return, without input tax calculation, regardless of turnover. |
2. The two reporting modes (the “When”)
The reporting mode defines the event that triggers your tax liability in your invoicing software:
Agreed consideration
According to agreed consideration (default): VAT is due as soon as you issue the invoice. Even if the customer pays after 30 or 60 days, VAT must be declared for the period in which the invoice was issued. This is the standard mode for companies keeping full accounts (debtors/creditors).
Received consideration
According to received consideration (upon request): VAT is due only when you receive the payment. As long as the invoice has not been paid, there is nothing to declare.
Advantage: A major benefit for your cash flow, as you never pre-finance VAT for your customers. This mode requires a written request to the FTA.
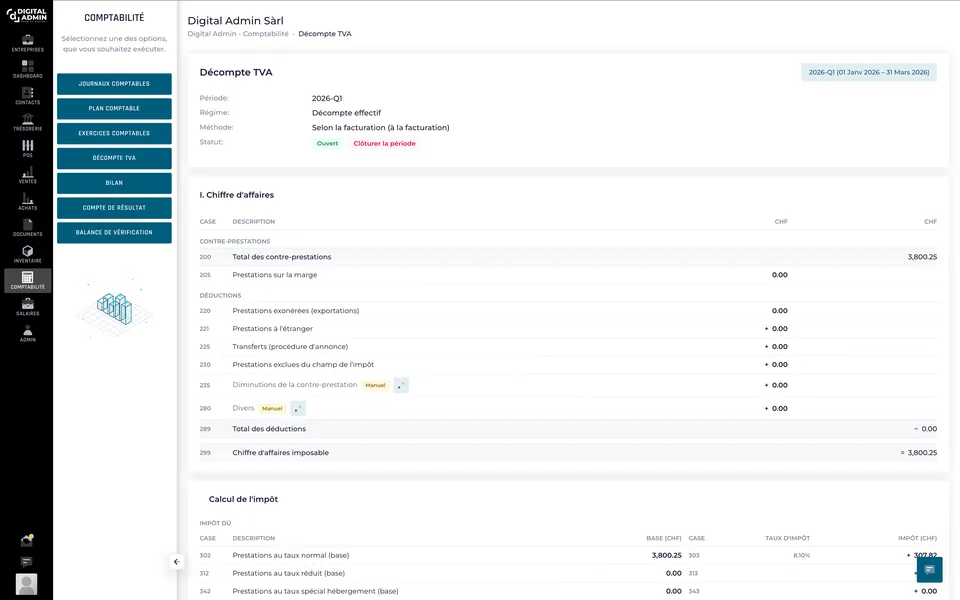
Discover the VAT feature in our application
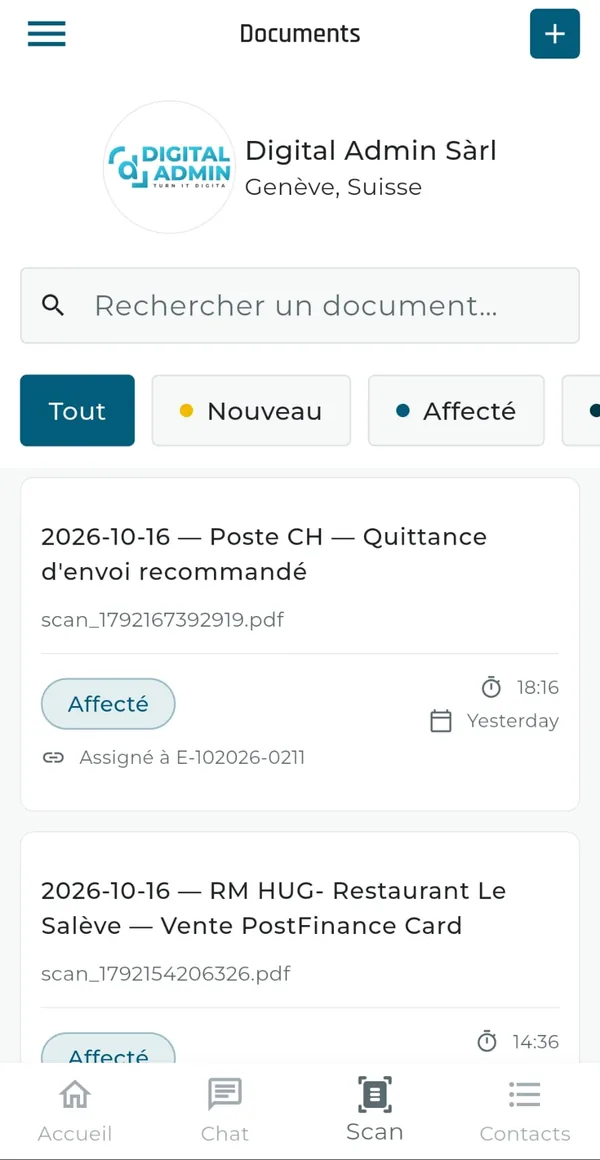
With Digital Admin App, you can manage your Swiss VAT independently: automatic calculations, returns in eCH format and pre-submission checks — directly from your application.
Let's talk about your VAT situation
Briefly describe your activity and your current VAT situation. We analyse your case and get back to you within 24 hours with a clear and non-binding response.
Marianni Morillo
Administrator
When you write to us, chances are I'm the one who will reply.